
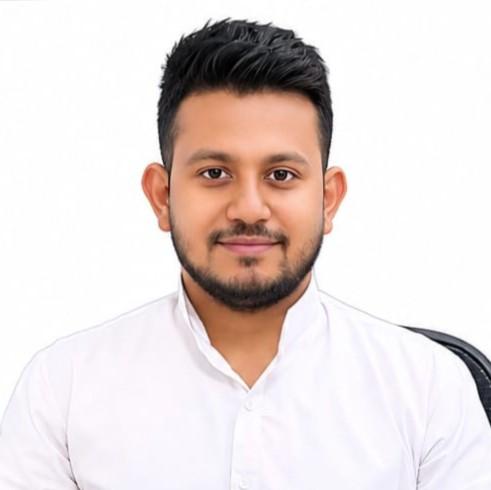
Puspendu Saha
Mathapur Road Purba, Pratapnagar, Nabadwip, Nadia, WB
Summary
Results-driven Credit Manager with expertise in credit risk assessment, loan appraisal, and financial analysis. Specialises in credit underwriting, portfolio management, and NPA management to minimise credit risk and ensure regulatory compliance. Committed to enhancing portfolio quality and driving sustainable growth and profitability for the organisation.
Overview
2
2
Languages
12
12
years of professional experience
Work History
Branch Credit Manager
Piramal Finance Limited
Ranaghat
02.2024 - Current
**Review loan applications and customer financial documents. **Analyse the customer's income, repayment capacity, and existing liabilities. **Evaluate credit bureau reports such as CIBIL. **Assess the customer's creditworthiness and repayment history. **Identify high-risk customers before loan approval **Evaluate loan proposals according to company credit policies. **Ensure compliance with lending guidelines and eligibility criteria. **Approve or recommend loans within the delegated authority. **Identified potential credit risks and implemented preventive measures to safeguard loan portfolio. **Maintain a healthy balance between business growth and credit quality. **Maintain WIP file within TAT **Ensure proper KYC and customer documentation. **Verify income proof, bank statements, and other financial documents. **Ensured legal and technical verification for all loan applications. **Check the accuracy and completeness of loan files before disbursement. **Prevent fraudulent applications and documentation. **Ensure loans are disbursed only after completing all credit conditions. **Coordinate with sales, operations, Technical, Legal, FI, FCU and RCU teams. **Verify compliance with sanction terms and conditions. **Monitor the accuracy of loan amounts, tenure, interest rates, and repayment schedules. **Monitor monthly EMI repayment performance. **Track overdue accounts and bounced EMIs. **Coordinate with collection teams for timely recovery. **Monitor overdue buckets such as 1–30, 31–60, 61–90, and above 90 days. **Identify reasons for payment defaults and recommend corrective action. **Monitor the company's overall loan portfolio. **Control delinquency and NPA levels. **Analyse portfolio quality and identify risky segments. **Monitor PAR (Portfolio at Risk). **Developed strategies to reduce loan defaults and enhance collection efficiency. **Guide and supervise credit officers and credit analysts. **Set targets and monitor team performance. **Train team members on credit policies and risk assessment. **Coordinate with sales, operations, Technical, legal, and collection departments. **Ensure smooth coordination between business growth and risk management. **Prepare daily, weekly, and monthly credit reports. **Monitor loan sanctions and disbursement. **Prepare overdue and collection performance reports. **Analyse rejection rates and approval ratios. **Submit portfolio quality and risk reports to senior management. **Ensure compliance with company lending policies. **Follow applicable RBI guidelines for regulated lending entities. **Ensure proper KYC and AML compliance. **Maintain transparency in loan processing and customer communication. **Support internal audits, statutory audits, and regulatory inspections.
- Collaborated with team members to achieve target results.
- Managed complaints with calm, clear communication and problem-solving.
- Maintained clean, safe working environments to eliminate accident risks.
Branch Credit Manager (Two Branch Managing)
Chola Investment and finance company Limited
Krishnanagar, Kalyani, India
12.2022 - 02.2024
Credit manager
Fullerton India Credit Company Limited
Raghunathganj, Murshidabad, India
03.2022 - 12.2022
Deputy Credit Manager (Two Branch Managing)
Annapurna Finance Private Limited
Barddhaman, Asansol, India
08.2021 - 02.2022
Branch Credit manager (Two Branch Managing)
Veritas Finance Private Limited
Kalna, Katwa, India
06.2020 - 06.2021
Credit officer
HDFC Bank Limited
Kalna, India
06.2018 - 03.2020
Sales and Collection
Vodafone Distribution Point
Krishnanagar, India
01.2015 - 06.2018
Education
Master of Business Administration - Banking and Finance
vivekananda global university
Jaipur, Rajasthan2026
Bachelor of Commerce - Commerce
Nabadwip Vidyasagar College (Kalyani University)
Nabadwip, West Bengal01-2013
Higher Secondary Education (WBCHSE) - Commerce
Nabadwip Bakultala High School
Nabadwip, West Bengal01-2010
Secondary Education (WBBSE) -
Nabadwip Bakultala High School
Nabadwip, West Bengal01-2008
Skills
- Microsoft Word, Microsoft Excel
- Credit risk assessment
- CIBIL analysis
- KYC verification
- Collections strategy
- Delinquency tracking
- Portfolio management
- Regulatory compliance
- Data analysis
- Strategic planning
- Stakeholder coordination
- Team leadership
- Team motivation
- Policy adherence
- Problem-solving
- Communication skills
- Microsoft Excel
- Microsoft Word
- Leadership
LANGUAGE SKILLS
Mother tongue: Bengali
Proficient
C2
Other language(s): English , Hindi
Upper Intermediate
B2
INTERESTS
- Listening Music, Traveling, Watching Comedy Show, Participate in Social Activities, Drawing, Playing Cricket, Gardening.
DECLARATION
I hereby declare that all the information provided above is true and correct to the best of my knowledge and belief. I take full responsibility for the accuracy of the information furnished in this resume.
Personal Details
- Date of Birth: 03/02/1991
- Nationality: Indian
- Marital Status: Single
- Gender: Male
- Religion: Hindu
- Father's Name: Nirendra Saha
Timeline
Branch Credit Manager
Piramal Finance Limited
02.2024 - Current
Branch Credit Manager (Two Branch Managing)
Chola Investment and finance company Limited
12.2022 - 02.2024
Credit manager
Fullerton India Credit Company Limited
03.2022 - 12.2022
Deputy Credit Manager (Two Branch Managing)
Annapurna Finance Private Limited
08.2021 - 02.2022
Branch Credit manager (Two Branch Managing)
Veritas Finance Private Limited
06.2020 - 06.2021
Credit officer
HDFC Bank Limited
06.2018 - 03.2020
Sales and Collection
Vodafone Distribution Point
01.2015 - 06.2018
Master of Business Administration - Banking and Finance
vivekananda global university
Bachelor of Commerce - Commerce
Nabadwip Vidyasagar College (Kalyani University)
Higher Secondary Education (WBCHSE) - Commerce
Nabadwip Bakultala High School
Secondary Education (WBBSE) -
Nabadwip Bakultala High School